THE TAKEAWAY
A ride can be covered by insurance and still leave you with costs. Knowing your cost sharing and the type of ambulance benefit you have is a useful first step.
Does covered by insurance mean paid in full?
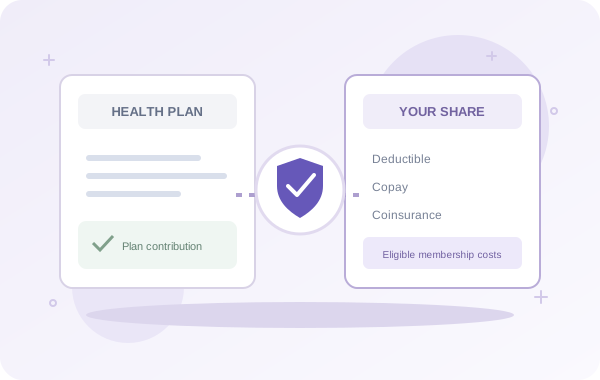
Health insurance may cover an ambulance ride that meets the plan’s requirements. It may still leave you with a deductible, copay, or coinsurance, so “covered” and “paid in full” are different outcomes.
Start with the ambulance section of your health plan’s benefits. Look at ground and air transport separately, then find the deductible, copay, or coinsurance that applies. Those details turn a broad promise of coverage into something you can plan around.
Ambulance deductibles, copays, and coinsurance explained
- Deductible: the amount you generally pay for certain eligible services before your health plan begins paying.1
- Copay: a fixed payment required for a covered service.2
- Coinsurance: your percentage of eligible costs, commonly applied after the deductible.3
Paying a monthly health insurance premium does not automatically remove these costs. Check the terms of your particular health plan rather than assuming the ambulance benefit works like an office visit.
An ambulance cost example after insurance
A $2,500 approved ambulance bill
Assume $1,000 of deductible remains and 20% coinsurance applies to the remaining $1,500. The estimated patient share is $1,000 + $300 = $1,300.
This example assumes the insurer approves the full bill. It excludes copays, denied charges, and legally permitted balance bills. It is not a quote or claim decision.
The lesson is the relationship between the numbers: a deductible and a percentage can add up quickly. You can change the inputs in our ambulance cost calculator to explore the same idea.
Out-of-network ambulance bills and Medicare costs
For many covered air ambulance services, federal law limits out-of-network balance billing. Ground ambulance services generally fall outside those federal protections; state rules may differ. Ordinary cost sharing can still matter.4
With Original Medicare Part B, ambulance services generally involve 20% of the Medicare-approved amount after the deductible. Other coverage may help with that share.5
Write down what applies to you. A useful checklist is: ground benefit, air benefit, remaining deductible, coinsurance, other coverage, and any questions to ask your insurer.
Prepare for ambulance insurance gaps before an emergency
EMS360 offers three focused choices: Ground, Air, and Ground + Air. Each addresses eligible emergency ambulance costs under the applicable Membership Agreement. The combined product brings both transport benefits together.
Choose the emergency benefit you want, then decide whether the membership should include you, your family, or your household. Review eligibility and exclusions alongside your existing health plan. These memberships supplement your financial protection and do not replace health insurance.
Enrollment is a decision to make before an emergency. Benefits begin after successful enrollment payment; earlier events are not covered. In a medical emergency, call 911 and focus on getting care.
Sources & further reading
- HealthCare.gov: Deductible
- HealthCare.gov: Copayment
- HealthCare.gov: Coinsurance
- CMS: Medical bill rights when using insurance
- Medicare: Ambulance services coverage
This article is educational. Your health plan and applicable EMS360 Membership Agreement determine coverage, eligibility, exclusions, and claim requirements. In a medical emergency, call 911.